
T3 Trust Return Preparation in Ontario
Accurate trust tax reporting for trustees, executors, and estate representatives.
Preparing a T3 Trust Income Tax and Information Return involves more than reporting the income earned by a trust. Trustees and estate representatives may also need to account for capital transactions, beneficiary allocations, information slips and beneficial ownership reporting.
Ram BG CPA provides T3 trust return preparation for eligible trusts and estates in Ontario. The service covers the review of available trust and financial records, calculation of taxable income, preparation of applicable schedules and T3 slips, and filing with the Canada Revenue Agency (CRA).
The filing requirements depend on the trust's structure, tax year and activities. Ram BG CPA can review your circumstances and clarify the tax preparation work required before the engagement begins.
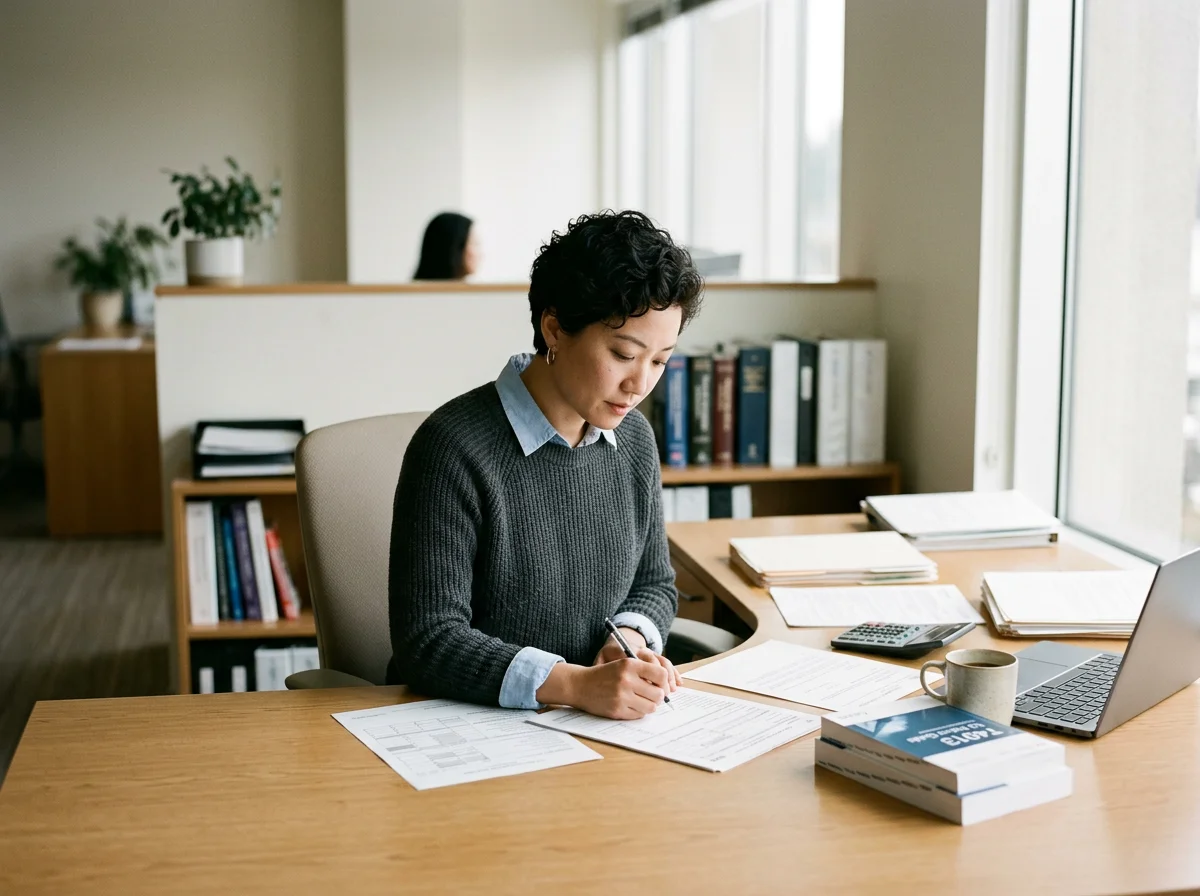
Understanding the T3 Trust Income Tax Return
A T3 return reports a trust's income, tax position and relevant information about its beneficiaries and other reportable entities.
The T3 Trust Income Tax and Information Return is used to report the income and tax obligations of a trust or estate. It also serves as an information return, providing the CRA with details about the trust and, where required, its trustees, settlors, beneficiaries and controlling persons.
A trust may earn income from several sources, including:
Interest and investment income.
Dividends.
Rental income.
Business or other income.
Capital gains from the sale or deemed disposition of assets.
The return records the trust's income and applicable deductions, calculates taxable income and tax payable, and reports amounts allocated or designated to beneficiaries.
Where income is allocated or designated to beneficiaries under the applicable tax rules, the trust may need to prepare T3 slips and a T3 Summary. Beneficiaries generally use the information on their slips when preparing their own income tax returns.
How a T3 Return Differs From T1 and T2 Returns
The three returns serve different purposes:
T1 Personal Income Tax Return: Reports an individual's income, deductions and tax position.
T2 Corporate Income Tax Return: Reports the income and tax position of a corporation.
T3 Trust Income Tax and Information Return: Reports the income, tax position and relevant information of a trust or estate.
A beneficiary's T1 return does not replace the trust's T3 filing obligation. Similarly, filing a deceased person's final T1 return does not automatically meet the reporting requirements of their estate.
Trusts and Estates That May Require T3 Filing Support
] Trustees and estate representatives may have T3 reporting responsibilities even when a trust has limited income or activity. T3 Trust Return Preparation may be relevant to different types of trusts and estate arrangements. The filing obligation depends on the legal structure, tax residency, trust type, assets, transactions and applicable CRA exemptions.
Ram BG CPA can review the available information for engagements involving:
Who Needs T3 Trust Return Services?
Family Trusts
Family trusts may hold investments, shares in private corporations, or other assets for the benefit of family members. Their reporting may involve investment income, dividends, capital gains, and allocations to beneficiaries. organize
Testamentary Trusts
A testamentary trust is generally created as a consequence of an individual's death, including arrangements established under a will. Its tax reporting depends on the terms of the trust, the assets held, and income or transactions during the year.
Graduated Rate Estates (GREs)
An estate that meets the CRA's conditions may qualify as a Graduated Rate Estate for up to 36 months following the individual's death. This status affects the estate's tax treatment and certain filing arrangements.
Inter Vivos Trusts
An inter vivos trust is generally established during the settlor's lifetime. Depending on its activities and structure, it may need to report investment income, rental income, capital transactions and beneficiary allocations.
Estates of Deceased Individuals
An estate may earn income, receive investment distributions or dispose of assets after an individual's death. These activities can create a separate T3 filing obligation in addition to the deceased person's final T1 return.
Trusts Holding Investments or Income-Producing Assets
Trusts holding bank deposits, investment portfolios, shares, rental properties or other income-producing assets may need to report income and capital transactions. The tax treatment depends on the nature of the asset and the trust's circumstances.
T3 Tax Preparation, Income Reporting and Information Returns
The preparation process covers the trust's tax position, applicable schedules, and beneficiary reporting based on the records provided.
A T3 return needs to reflect the trust's income, expenses, transactions, and reporting obligations for the relevant tax year. The work required will depend on the trust's activities and the completeness of its records. The following areas may form part of a T3 tax preparation engagement, where applicable and agreed.
-
The first step is to understand the trust's structure and determine which tax reporting requirements may apply.
The review may include:
Trust deed, will or other relevant documentation.
Trust account number and previous T3 returns.
Trust type and tax year-end.
Information about trustees, settlors and beneficiaries.
Changes to the trust's structure or beneficiaries.
Applicable annual filing and information-reporting requirements.
A legal review or interpretation of the trust deed is not included in tax preparation services.
-
The trust's financial records are reviewed to identify income and expenses that may be relevant to the T3 return.
Depending on the trust's activities, this may include:
Interest and dividend income.
Investment distributions.
Rental income and eligible expenses.
Business or other income, where applicable.
Carrying charges and other potentially deductible expenses.
Income received from foreign sources.
The tax treatment of an expense depends on its nature, supporting documentation and the applicable tax rules. Not every expense paid by a trust is deductible.
-
The trust's income is reviewed and adjusted for applicable deductions, tax treatment and other relevant provisions. The resulting taxable income and tax payable are calculated for the year.
This may involve reviewing:
Income retained by the trust.
Deductions and eligible expenses.
Capital gains and allowable capital losses.
Losses carried forward or back, where applicable.
Tax credits and other relevant calculations.
The tax treatment can differ between trust types. For example, a qualifying Graduated Rate Estate may have access to graduated tax rates during its qualifying period, while many other trusts are subject to different trust tax rules.
-
Where trust income is paid, payable or designated to beneficiaries under the applicable rules, the trust may need to report those amounts and issue T3 slips.
This work may involve:
Reviewing income allocated or designated to each beneficiary.
Determining the character of the amounts being reported.
Preparing T3 slips where required.
Preparing the T3 Summary.
Checking that beneficiary reporting agrees with the trust return.
A T3 slip is an information statement. It does not mean that every amount distributed by a trust is automatically taxable income to the recipient. Income allocations, capital distributions and other transfers can have different tax consequences.
-
Where T3 slips are required, the T3 Summary reports the total amounts allocated or designated to beneficiaries. The summary must reconcile with the individual slips and the relevant amounts reported on the trust return.
-
Schedule 15 reports specified information about a trust's reportable entities where the trust is subject to the applicable beneficial ownership reporting requirements.
Reportable entities generally include:
Trustees.
Settlors.
Beneficiaries.
Controlling persons.
The information requested may include names, addresses, dates of birth for individuals, countries of residence and tax identification numbers.
Schedule 15 is not required for every trust. Listed trusts and other arrangements may qualify for exceptions. Where it is required, the information must be considered for the relevant tax year, even if the trust has no income to report.
-
A trust may have capital gains or losses when it sells, transfers or is deemed to dispose of capital property. These transactions need to be reviewed and reported using the applicable schedules.
The review may involve:
Purchase and sale records.
Adjusted cost base information.
Proceeds of disposition.
Capital improvements and other relevant adjustments.
Deemed dispositions, where applicable.
Capital losses and available carryforward balances.
A transfer or distribution of property to a beneficiary may have tax consequences even when no cash changes hands. The treatment depends on the nature of the property, the trust and the applicable provisions of the Income Tax Act.
-
An estate or trust that is being wound up may require a final T3 return. The final reporting period, asset distributions, income and capital transactions need to be reviewed.
For a qualifying Graduated Rate Estate, the final filing deadline is generally 90 days after the date the estate ceases to exist. For other trusts, the deadline is generally 90 days after the relevant tax year-end.
A CRA clearance certificate may also be relevant before estate or trust property is distributed. Obtaining a clearance certificate and administering the estate are separate matters from preparing the T3 return.
-
Once the return and applicable schedules have been reviewed and approved, the filing process can be completed using the appropriate CRA filing method.
The engagement may include:
Preparation of the T3 return and agreed schedules.
Preparation of related T3 slips and summary, where applicable.
Electronic filing where the return is eligible and the required authorisation is in place.
Providing the trustee or representative with copies of the completed filing documents.
Clarifying routine questions about the filed return.
CRA reassessments, objections, voluntary disclosures, complex correspondence, and amended returns are not automatically included in standard preparation fees. They can be discussed and scoped separately.
Scope Clarification: T3 Trust Return Preparation is a tax compliance service. It does not automatically include:
Creating or establishing a trust.
Drafting or amending trust deeds or wills.
Legal interpretation of trust documents.
Probate applications.
Estate administration or executor services.
Asset valuation or investment management.
Decisions about distributing trust assets.
Ongoing bookkeeping or financial administration.
Legal advice or comprehensive estate planning.
These matters may require a lawyer, estate professional, investment adviser or another specialist. Additional accounting and tax work can be considered separately where appropriate.
Trust Tax Reporting With Direct Professional Involvement
Trust tax reporting requires careful attention to the records, transactions and filing obligations relevant to each arrangement. Ram BG CPA provides a direct point of contact throughout the agreed tax preparation engagement.
CPA, CA Credentials
Ram BG operates as a sole practitioner through RAM CPA Professional Corporation. Verify good standing with CPA Ontario by clicking on the names above.
Direct Access to Your CPA
Ram CPA will be directly involved with each file and will be the sole point of contact. Clients files will receive individual attention from Ram CPA rather than being passed between multiple staff members.
Experienced Canadian Corporate Tax Accountant
Ram CPA has almost a decade of experience in the CCPC/Canadian business tax landscape. He has worked extensively with owner managers across industries such as hospitality and restaurants, medical and dental practices, professional services, trades, construction, hospitality and general IT consulting.
A Digital, Paperless Workflow
Ram CPA is fully paperless and utilities a range of best in industry tools and softwares for information gathering, document sharing and digital signatures. In other words, Ram CPA is fully digital.
How the T3 Filing Process Works
Each engagement progresses from an initial assessment of business requirements to the preparation and issuance of compiled financial information.
A compilation engagement follows a defined process under CSRS 4200. The accountant needs to understand the business and the intended use of the financial information before accepting the engagement.
Step 1 – Initial Discussion and Engagement Assessment
The process begins with a discussion about the business, its accounting records, and why the financial statements are required.
The intended use of the compiled financial information is an important consideration. If a lender or another third party will use the statements, its reporting requirements should be established before the engagement proceeds.
Step 2 – Collection of Accounting Information
The business provides the accounting records and supporting information needed for the engagement. Depending on the business, these may include:
Trial balance and general ledger
Bank and credit card records
Accounts receivable and payable information
Revenue and expense records
Payroll and related records
Details of assets, liabilities, and loans
Previous financial statements, where available
Relevant year-end schedules and supporting documents
Step 3 – Understanding the Records and Basis of Accounting
The accountant obtains an understanding of the business, its accounting systems and the basis of accounting to be applied. The basis of accounting is discussed with management, which is responsible for selecting it. The financial information must include an appropriate description of that basis.
Step 4 – Compilation and Preparation of Financial Information
The accountant assists management in preparing the agreed financial information using the records and explanations provided. Any significant matters or judgments requiring management's input are discussed. If information appears misleading or requires clarification, the matter must be addressed before the engagement can be completed.
Step 5 – Management Acknowledgement and Report Issuance
Management reviews the final compiled financial information and acknowledges responsibility for it. Once the engagement requirements are completed, the accountant issues the Compilation Engagement Report under CSRS 4200.systems,
[Important Process Note]
Management remains responsible for the underlying accounting records, the accuracy and completeness of the information provided, the selection of the accounting basis and the final compiled financial information. The accountant's role is to assist with its preparation in accordance with the standard.
Digital Accounting and Tax Preparation
Ram BG CPA uses professional tax software and digital accounting tools to support its corporate tax preparation and document management process.
Corporate Tax Support Across Industries
Ram BG CPA works with small businesses and owner-managed corporations across a range of industries. The firm is not limited to a single industry, and the requirements of each engagement are considered individually.
Relevant business types may include:
Professional services: Consultants, marketing agencies, designers and other professional service businesses
Technology and IT: Software developers, IT contractors and digital businesses
Health and medical: Incorporated health professionals, clinics and other healthcare-related businesses
Trades and contracting: Trade contractors and service-based operating businesses
Holding companies: Corporations holding investments, real estate or other corporate assets
The nature of the business, its records and its tax reporting requirements will help determine the scope of the engagement.
Virtual accounting services across Ontario
Ram BG CPA provides virtual accounting and compilation engagement services to eligible businesses in Ontario, with a focus on Mississauga and the Greater Toronto and Hamilton Area. Businesses looking for a compilation engagement in Ontario, a CSRS 4200 accountant, or Notice to Reader financial statements can discuss their reporting requirements with the firm.
Mississauga
Compilation engagement and accounting services for eligible businesses based in Mississauga.
Toronto and the Greater Toronto Area
Virtual accounting support for eligible businesses in Toronto and surrounding communities.
Brampton, Oakville, and Burlington
Services for businesses in these communities, subject to engagement requirements.
Hamilton and the Greater Hamilton Area
Virtual accounting services for eligible businesses in Hamilton and surrounding areas. The firm may also consider engagements elsewhere in Canada, depending on the nature of the work and applicable professional and geographic requirements.
Important Information About Compilation Engagements and CSRS 4200
-
A compilation engagement is a professional accounting service in which an accountant assists management in preparing financial information based on information provided by the business. The engagement is performed under CSRS 4200 and results in a Compilation Engagement Report. It does not provide assurance on the financial information.
-
CSRS 4200 stands for Canadian Standard on Related Services 4200 – Compilation Engagements. It establishes the professional requirements for accepting, performing and reporting on compilation engagements in Canada.
-
The terms are related, but they refer to different reporting frameworks. Notice to Reader was the terminology commonly used under the previous compilation standard, Section 9200. CSRS 4200 replaced that standard, and the current report is called a Compilation Engagement Report.
-
Notice to Reader financial statements is a commonly used term for financial statements prepared under the previous compilation reporting framework. Today, the equivalent service is a compilation engagement under CSRS 4200, accompanied by a Compilation Engagement Report.
-
No. A compilation engagement does not provide assurance. The accountant assists management in preparing financial information but does not perform the procedures required for an audit or review. The Compilation Engagement Report clearly explains this limitation.
-
The main difference is the level of work performed and assurance provided:
Compilation: The accountant assists management in preparing financial information. No assurance is provided.
Review: The accountant performs inquiry and analytical procedures and provides limited assurance.
Audit: The accountant performs procedures to obtain reasonable assurance and expresses an audit opinion.
The appropriate engagement depends on the purpose of the financial statements and the requirements of their intended users.
-
Depending on the agreed scope and basis of accounting, compiled financial information may include a balance sheet or statement of financial position, an income statement or statement of earnings, a statement of retained earnings where applicable, and supporting notes. The exact presentation depends on the business and the purpose of the financial information.
-
The basis of accounting describes the accounting principles and methods used to prepare the financial information. Management is responsible for selecting an appropriate basis of accounting. The compiled financial information must also include a note describing the basis used.
-
Not necessarily. Accounting Standards for Private Enterprises (ASPE) is one possible financial reporting framework, but a compilation engagement does not automatically mean that the financial statements comply with ASPE. The applicable basis of accounting must be determined and described appropriately. The statements should not claim compliance with ASPE unless its requirements have been met.
-
Not automatically. A compilation engagement involves assisting management with the preparation of financial information using the records provided. Ongoing bookkeeping, transaction recording, bank reconciliations and extensive catch-up work may require additional services or a separately agreed scope of work.
-
No. A compilation engagement does not require the accountant to verify the accuracy or completeness of the underlying financial information through audit or review procedures. Management remains responsible for maintaining the accounting records and providing complete and accurate information.
-
Ram BG CPA provides both compilation engagement services and corporate tax return preparation. These services may be discussed together, but the work involved and the applicable fees will depend on the business's requirements and the agreed engagement scope.
Other Accounting and Tax Services
-
![]()
Small Business Accounting
Accounting support for small businesses that need help maintaining financial records and preparing for year-end tax compliance.
-
![]()
Bookkeeping Services
Bookkeeping support to help maintain organised financial records and simplify the preparation of year-end corporate tax returns.
-
![]()
HST / GST Registration and Filing
Support with relevant sales tax registration, return preparation and filing requirements, depending on the business’s circumstances.
-
![]()
CCPC Tax Planning and Advisory
Separate tax planning services for eligible private corporations, including relevant owner compensation and corporate structuring considerations.
-
![]()
Personal Tax Return Preparation
Personal income tax preparation for individuals, including business owners who need to manage their personal tax obligations alongside their corporate tax responsibilities.
Get Professional Support With Your Compilation Financial Statements
If your business needs financial statements for year-end reporting, corporate tax preparation, internal use, or a financing discussion, the first step is to understand the intended purpose and reporting requirements.
Ram BG CPA can discuss whether a compilation engagement under CSRS 4200 is appropriate for your business and explain the information required to get started.